

Knowledge Hub
10
5
min read
AI in Telecom: From Bolt-On Tools to a Native Reasoning Layer
AI in telecom is a native reasoning layer, not bolt-on automation. See the use cases, the benefits, and the challenges operators face. Find out where it fits.
What AI in Telecom Actually Is
AI in telecom is a native reasoning layer embedded across the operator stack, from the radio access network to billing, not a set of bolt-on tools attached to a legacy system. It reasons over the data the network already emits and acts on it inside the platform that carries the traffic. Bolt-on AI sits on top of the stack and recommends; native AI sits inside it and decides.
The distinction sets the ceiling on what an operator can achieve. An operator that treats AI as a bolt-on buys point tools and integrates them one by one. An operator that treats it as a native layer rebuilds the data and model layers so every service inherits intelligence by default.
What is AI in telecom?
AI in telecom is the application of machine learning and generative models across network operations, customer experience, and monetisation, embedded natively in the operator stack. It predicts network and customer events, generates offers and configurations, and automates workflows the network executes directly.
Why Bolt-On AI Fails
Bolt-on AI fails because it reads a copy of the network after the fact, while native AI reasons over the live stack and writes decisions back into it. AI in telecom works like the network control plane: it does not just carry the service request, it decides how each request is handled. An operator that bolts a model onto a legacy BSS has built a control plane that can read the network but cannot steer it.
Three structural limits hold bolt-on AI back.
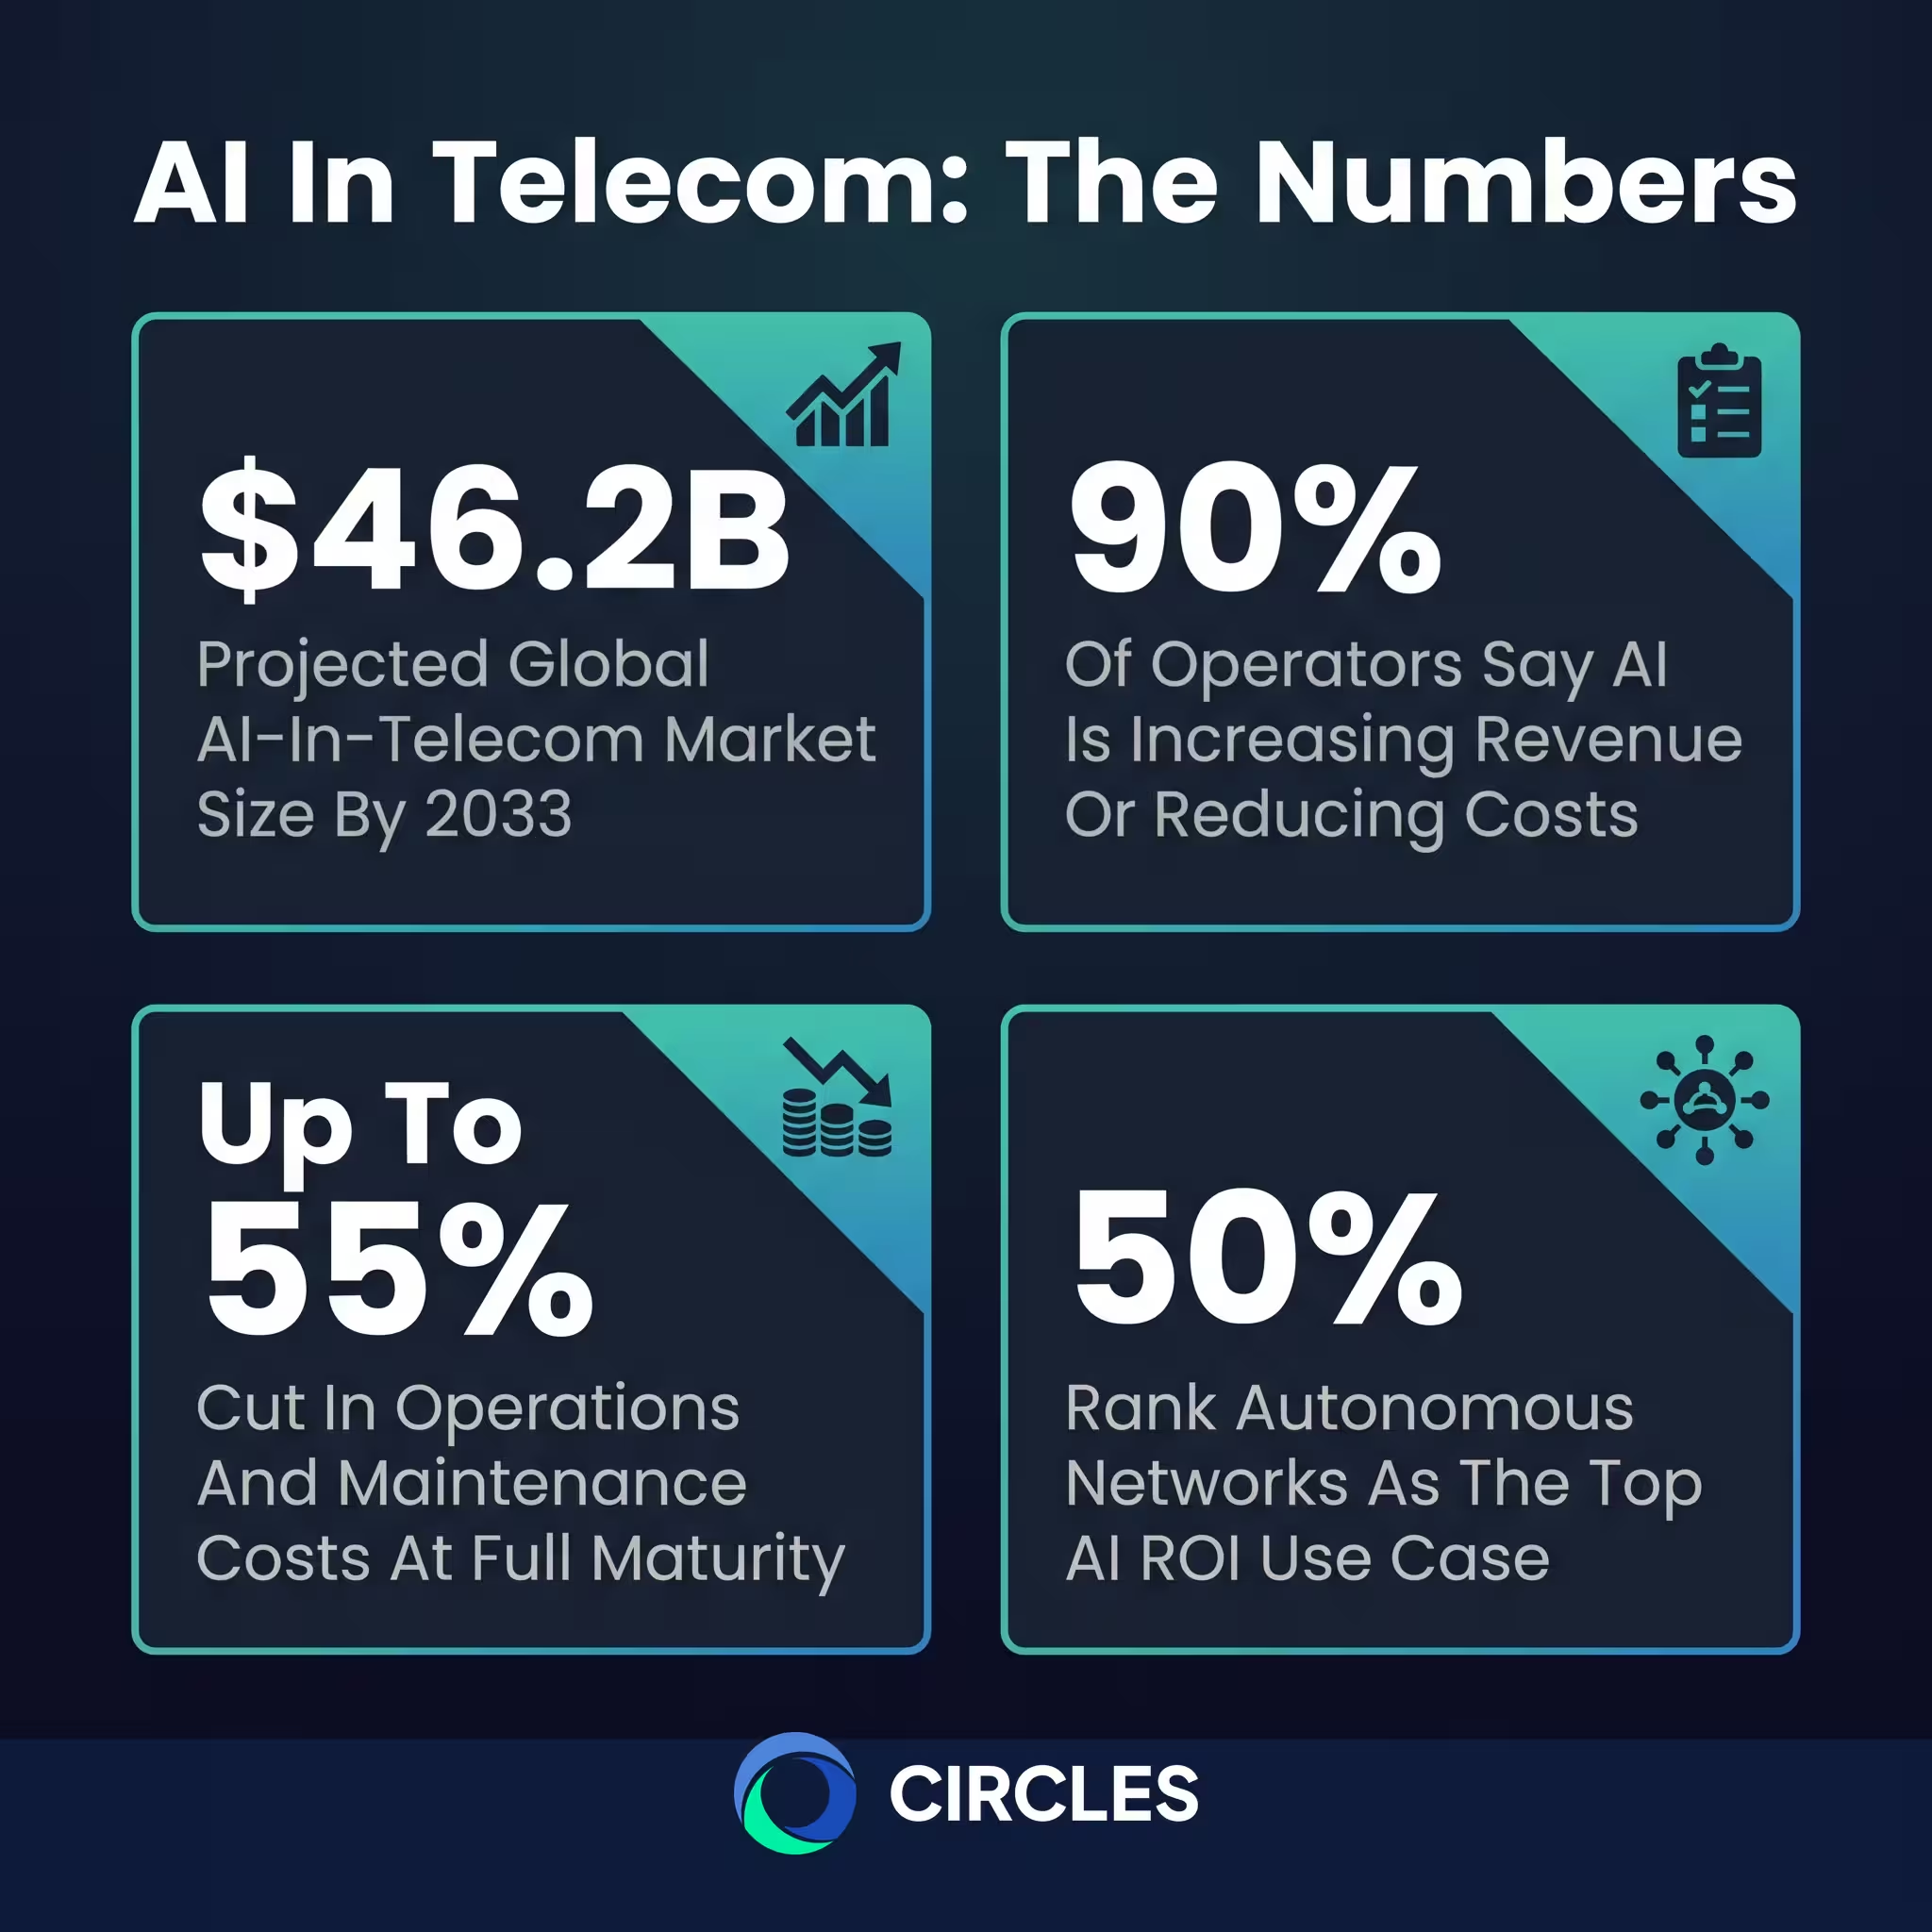
The industry has chosen the native footing. NVIDIA's fourth annual State of AI in Telecommunications survey (February 2026) found that 90% of respondents say AI is helping increase revenue and reduce costs, with autonomous networks the top return-on-investment use case at 50%, ahead of improved customer service (41%) and internal process optimisation (33%). Adoption keeps accelerating: 65% say network automation is now AI-driven, 60% are using or assessing generative AI (up from 49% a year earlier), and 89% plan to increase AI spend in 2026.
Autonomous networks are the clearest expression of the native model: a zero-touch operations target where the network detects, decides, and remediates routine events without a human in the loop, escalating only what genuinely requires judgement. A bolt-on architecture cannot reach zero-touch, because the human relay it depends on is exactly the touch the target is designed to remove.
Why does bolt-on AI underperform native AI in telecom?
Bolt-on AI reads exported data and hands a recommendation to a human to act on, so it lags the live network. Native AI reasons over the live stack and writes the decision back into orchestration, removing the human relay and the data-staleness gap.
The Technologies That Make It Native
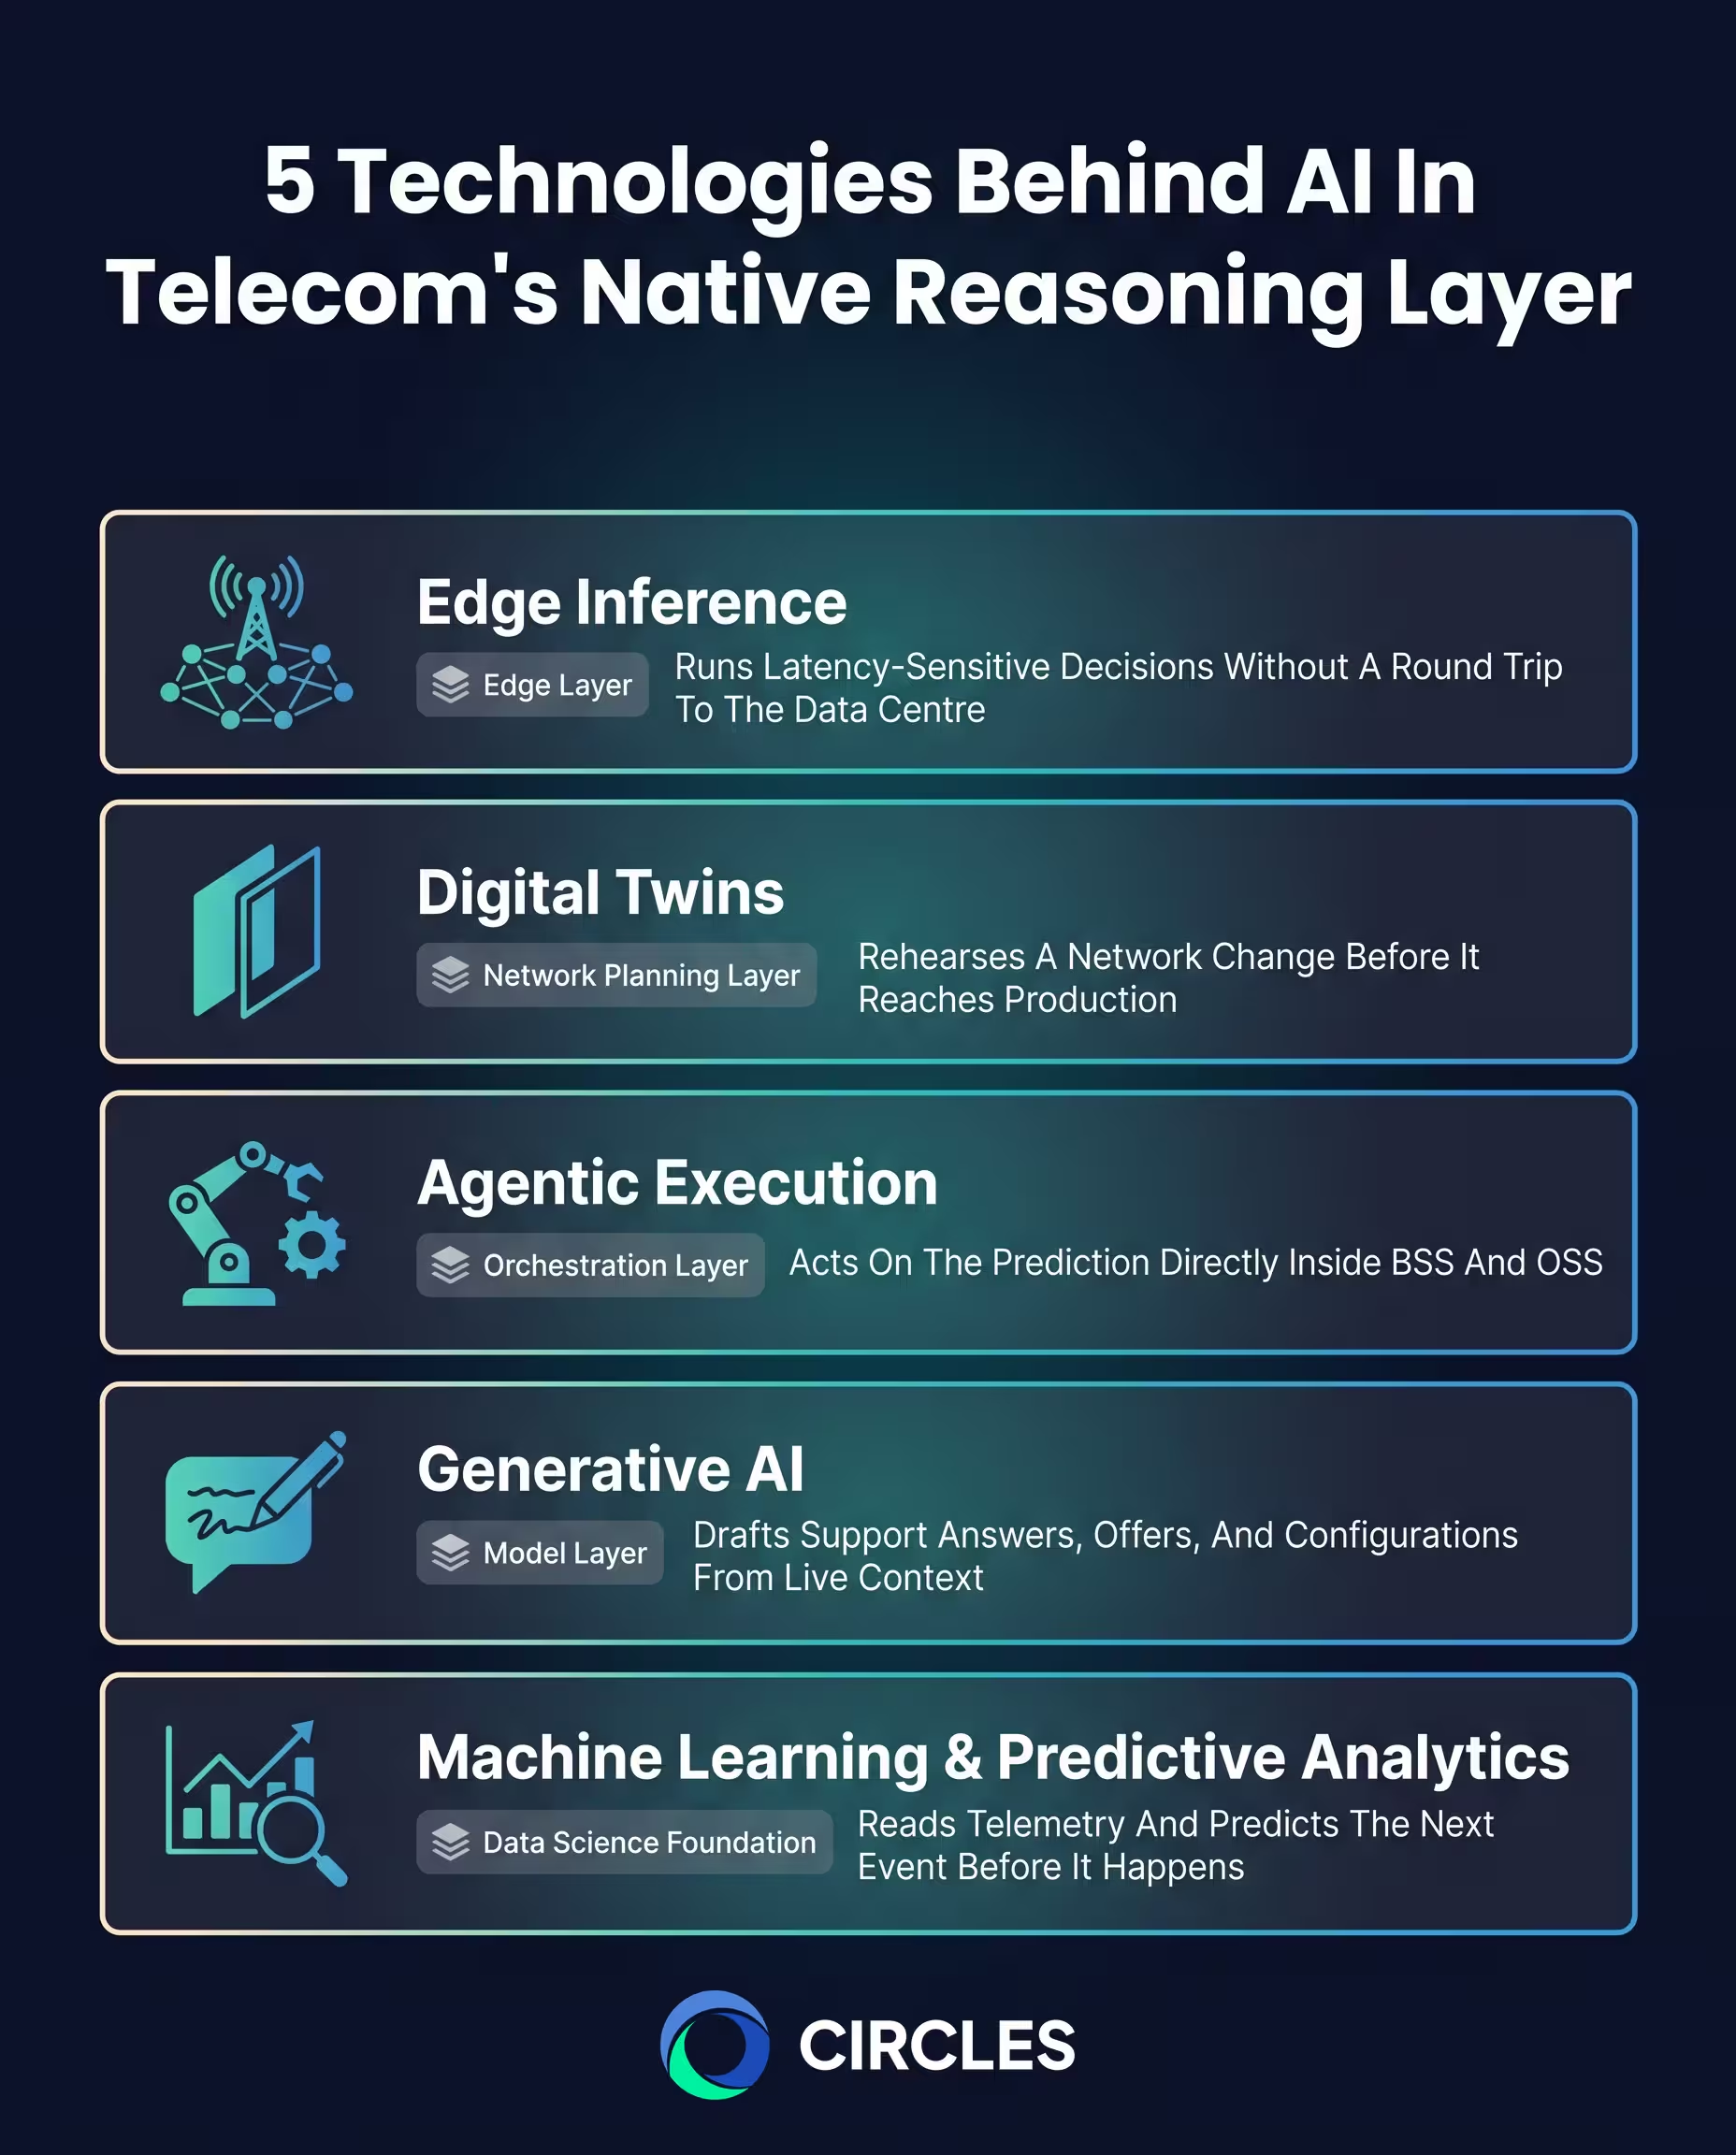
AI in telecom Embeds five component technologies into one reasoning layer, from the models that predict to the agents that execute, rather than five disconnected point tools bolted onto the stack. Each technology solves a distinct problem; the native layer is what lets them share one data foundation instead of five siloed ones.
Predictive analytics and machine learning supply the foundation every other technology reads from; generative AI and agentic execution turn a prediction into an action; digital twins and edge inference decide where and how fast that action runs. The data science layer that anticipates network and customer events sits beneath all five. Generative reasoning runs through the generative AI roadmap, execution through agentic AI, rehearsal through digital twins, and latency-sensitive inference through edge AI.
What technologies make up AI in telecom?
AI in telecom runs on five component technologies working as one layer: machine learning and predictive analytics (the foundation that reads telemetry and predicts events), generative AI (drafts responses and offers from live context), agentic execution (acts on the prediction inside BSS/OSS without a human relay), digital twins (rehearses network changes before deployment), and edge inference (runs latency-sensitive models at the point of need).
The Use Cases That Matter
AI in telecom concentrates in five use-case families, each a distinct reasoning problem running on the same native data foundation. The applications differ; the underlying integration does not.
Two of these use cases carry a measurable cost of inaction. Telecom fraud losses reached an estimated $38.95 billion in 2023, a 12% year-on-year increase, and a single hour of unplanned network outage costs an operator in the region of $400,000 in lost revenue. Fraud scoring, billing integrity, and revenue assurance run on the same native reasoning layer as churn and CX prediction: a joined view of billing, network, and usage data that flags an anomaly the moment it appears rather than at the next audit cycle. On the conversational side, the shift from scripted chatbots to agentic execution is already measurable at industry scale: Vodafone's SuperTOBi assistant lifted first-time resolution from 15% to 60% in Portugal and raised online NPS by 14 points to 64, evidence that the market rewards agents that resolve rather than agents that merely respond. Robotic process automation sits underneath all of it: the write path described under agentic execution above (service activation, data validation, billing correction) is what RPA looks like once it runs on a native reasoning layer instead of a scripted macro.
What are the use cases of AI in telecom?
The core use cases are network operations (fault prediction, RAN optimisation), customer experience (real-time personalisation and conversational resolution), retention (churn prediction), monetisation (dynamic offers), and trust and safety (fraud scoring, billing integrity, and governance). Each runs on the same native data foundation rather than a separate tool, which is why fraud detection, revenue assurance, and automated billing correction sit on the same architecture as churn prediction and CX personalisation instead of requiring separate point solutions.
The Benefits Operators See
AI in telecom delivers measurable gains in revenue, cost, and experience, because a native reasoning layer compounds value across every service it touches. The benefit is not a single feature; it is the multiplier across the stack.
McKinsey documents one European operator that raised marketing campaign conversion rates by 40% and a Latin American operator that lifted call-centre agent productivity by 25% through generative AI. At market scale, Grand View Research values the global AI-in-telecommunications market at $4.6 billion in 2025, projected to reach $46.2 billion by 2033, a 32.5% compound annual growth rate. Operator deployments confirm the pattern: povo2.0 (KDDI) reached 16-week launch cycles, an NPS gain of 30 points, an 8% ARPU lift, and over one million subscribers in year one. Maturity compounds the gains: TM Forum's *2025 Autonomous Operations Maturity Industry Insights* (IG1346) research, previewed via TM Forum's autonomous operations coverage, reports network maturity cuts operations and maintenance costs by up to 55%, raises customer satisfaction by 71%, and saves 21% of energy, and around 60% of operator AI deployments are already live, with 40% still in trial or planning. A separate deployment confirms the pattern from the retention side: an APAC operator using AI-driven customer value management reduced churn by 10% and increased cross-selling by 20%.
What are the benefits of AI in telecom?
The benefits are higher revenue (better conversion and ARPU), lower operating cost (automated network operations), and improved experience (real-time personalisation and faster resolution). A native layer compounds these because every service inherits the same intelligence.
Where the Native Layer Extends Across the Network
AI in telecom Synchronises with every major network initiative an operator runs, from 5G-Advanced rollouts to industrial IoT slicing, rather than sitting apart as a separate CX or marketing tool. An operator that treats AI as a customer-experience add-on misses the half of its value that lives in the network itself.
Network slicing is the clearest example. Dedicated throughput for enterprise and industrial customers depends on a model that predicts demand and allocates capacity before congestion hits, not a static reservation set once at launch. Operators running network slicing for industrial IoT and commercial network slicing for dedicated throughput use the same native reasoning layer that drives churn and CX prediction, applied to spectrum and capacity instead of subscriber behaviour.
The pattern holds as networks densify. 5G-Advanced and the eventual move to 6G both raise the number of live variables (beamforming, dynamic spectrum sharing, network energy states) beyond what a static configuration can hold, which is why the operators furthest along treat radio-layer optimisation as a data science problem before they treat it as a hardware one.
The same reasoning layer scales to device density and to energy. IoT deployments push the number of connected endpoints on the network into the billions, and a native layer that already predicts and allocates capacity for subscriber traffic extends the same prediction to machine traffic without a separate management plane. Energy follows the same logic: an AI-Native stack treats power consumption as a property of the architecture to optimise, not a cost to offset after the fact. Nokia's AVA Energy Efficiency software helped Globe Telecom in the Philippines cut annual RAN power consumption by 3% to 6% by shutting idle equipment during low-usage periods, evidence the same optimise-not-offset logic already runs in production at network scale. That is the sustainable-telco case Circles builds separately from the customer and network use cases above.
Does AI in telecom extend beyond customer experience and network operations?
Yes. AI in telecom also drives network slicing and capacity allocation for enterprise and industrial customers, predictive radio optimisation as networks move to 5G-Advanced and eventual 6G deployments, IoT device-density management, and energy optimisation across the network estate. These run on the same native data and model layers as churn prediction and customer experience, applied to spectrum, devices, and infrastructure rather than subscriber behaviour.
The Challenges Operators Face
The hard part of AI in telecom is not the model; it is the data foundation, the governance, and the legacy integration the native layer demands. Operators that underestimate these ship bolt-on tools and call it AI.
What are the challenges of AI in telecom?
The main challenges are data sovereignty (which jurisdiction governs subscriber data), legacy integration (the debt of bolting AI onto old systems), talent scarcity (the combined telecom-and-ML skill set is rare), trust and governance (making models explainable, auditable, and verified at every inference call), and implementation cost (each additional point tool adds its own integration and audit surface). Each is solved at the architecture layer, not by the model alone; a native stack that shares one data and model foundation resolves most of these at once instead of one tool at a time.
Build AI Into the Stack with Circles
A native AI layer orchestrates the operator stack, which catalyses the move from a connectivity business to a digital one. The build starts at the data and model layers, because a reasoning layer cannot act on data it cannot reach.
Operators that build on the AI-Native stack inherit reasoning across every service rather than bolting it on tool by tool. The next step is to map the AI-Native stack that embeds reasoning across the operator.